Showing posts with label bailout. Show all posts

Monday, 28 January 2013

The debate on Cyprus revisited

It seems like the media like uncertainty. They prefer it over times when credibility and logic define the world. The reason is obvious. In an uncertain world, the people want to receive as much information as they can get their hands on, and thus sales rise. However, for some inexplicable reason, the EU leaders appear to hold the view that uncertainty is good for them too.

An excellent example of the above is the latest disagreement between the ECB's president Mario Draghi and German Finance Minister Wolfgang Schaeuble, with the former stating that Cyprus could pose a systemically relevant danger to the Euro and the latter insisting that the country is not posing a danger to the Eurozone as a whole. In addition to this, Angela Merkel (a person who seems to prefer uncertainty and fragility over a strong economy) urged Cyprus to embrace economic reforms and fully implement laws against money laundering, but also said that Europe must show "solidarity" (whatever that may mean to her).
 
It seems as if we are watching the Greek situation all over again. The arguments move from "we will help" to "but [insert nation here] are doing this and that wrong", with Germany, (unfortunately for them and the Union) taking the position of the latter argument. Again, as stated on a previous article, the same question is posed: didn't the Germans, or whoever else holds that line of argument, know that there was money laundering in Cyprus in 2004 when they allowed it in the EU? How about in 2008 when it entered the Eurozone? Or a year ago? Was it something that just emerged over the past couple of weeks? Well, I would certainly hope not because the island had passed money laundering legislation much before its Eurozone entry and supposedly European legislators were overseeing them. 
Ireland, Portugal, Greece, Spain, Cyprus... Same old story isn't it?
Thanks to Polandball-News for the comic
Let us know remember what happened in the Cypriot economy: an economy with no recession since the 1970's, with GDP growth every year and a healthy banking system, crashed because of overexposure to the Greek market and the irrational Greek haircut (readers will also remember that I am still wondering why the Cypriot Finance Minister did not veto the Eurogroup decision concerning the 70% PSI haircut). We thus have a situation created by the mishandling of EU affairs and we just wash our hands off it.

Then there is talk about a systemic crisis, which is, in my humble opinion, irrelevant to the whole issue. What does it matter if the problem is systemic or not? What is the rationale behind this argument I fail to see. If someone is important then we assist him; if not then just let him collapse? This is Realpolitik even more than Henry Kissinger would have practiced. We are following the same erroneous ideologies which led to huge banks and companies which are too big to fail. 
 
To be fair here, the island would have gotten into a bad situation sooner or later. It needs stronger banking regulations and better implementation; its housing bubble would have also burst sooner or later. Yet, this does not mean that we should kill a person just because he has a bad case of flu. Given time and regulations the island may have pulled this off. We will never find out. Instead, we went for the crazy solution and created a mess we couldn't get out of. 
 
EU leaders are talking about whether they should give €9 or €10 billion to Cypriot banks, in addition to €6-7 billion for government expenses. They also seem to ponder whether the country's debt burden would be viable. I will spare them the thought and say it out loud as I have already said it before: it will not. The amount they are discussing is approximately 100% of GDP. Add to that an existing 80% debt-to-GDP ratio and you get an explosive situation. The brilliant solution for the brilliant €17 billion plan? A debt haircut which would affect Cypriot pension funds and banks. Who will again need more money. Money which will increase the debt burden and the need for a second haircut, with more money needed once again and so on... Simple as that. Yet, the problem could easily be solved with €3-4 billion (for details have a look at this). 

The most important point to be made here is that the EU (or Germany, or any other sharing the same views) is not going to hurt the "Russian oligarchs" by denying assistance to Cyprus. Just like the case with Greece, Spain and Portugal, it is not the rich who are affected; it's the ordinary people, those who are working day and night to earn enough to support their families. Billionaires with 80-metre yachts and huge deposits in almost every country in the world will not care so much if they loses some money. Sure, it will be upsetting but people live equally well with €5 billion as they did with €6. Not to mention that they will readily transfer that money to some other destination(s) in the blink of an eye. Yet, the person who is labouring all day in constructions or sales to save €100 a month for a rainy day cannot do that. 

If the EU leaders believe that denying money under cheap excuses like "money laundering" and "Russian oligarchs" is a good idea I have nothing more to add. I remind you though that these oligarchs and billionaires probably do not even live in Cyprus and most of them have deposits all around Europe as well.
 
What will be achieved is to set a precedent. And a very bad one too...

Tuesday, 15 January 2013

The Consequences of Exits

The case of Cyprus undoubtedly resembles the case of Greece. The amount the country needs is not large per se, as was the case with Greece, yet it is the equivalent of about 100% of its GDP, casting doubts on whether its lenders would ever be able to get their money back. In both cases, two options exist (and existed): either give the country all the money it requires to completely avoid default or let it fall and consequently exit the EU or more likely the Eurozone.

Advocates of the latter base their arguments mainly on whether it is rational or good practice to send good money after bad, or whether the EU will forever be the lender of last resort for troubled nations. As the number of Member-States which face trouble as a consequence of either irrational expenditure or housing bubbles continues to rise, proponents of the Pontius Pilate method (i.e. "I wash my hands of the subject") believe that a line should be drawn somewhere. Yet, where should that line be drawn and what are the consequences, if any, of that action?

During the most severe case of the Greek crisis over the last 6 months, notably over the summer months, it was stated that there was a great danger of Greece exiting the Union. What we have witnessed, however, is that Brussels made the decision to support the nation, both monetary as well as politically, given that the Greeks would play their part as well (which they did). Economic consequences would have been severe had Greece exited, but what of the consequences of a Cyprus exit or another small country's?

Here, the problem is mainly political and not an economic one. Having barely 0.2% of the EU's GDP does not qualify the island on being an economic force whatsoever. Nevertheless, think of the consequences of setting a precedent by letting Cyprus fail. The probability exists that all other countries will fear that their turn will come if they do not pay attention to their fiscal policies and they will do their best to follow suit on the instruction of the IMF and Brussels (or is it Berlin?). Yet, there is another possibility: that the Member-States will think that such a behaviour is not an acceptable one, and one could liken it with bullying: kick the little guy out so the medium ones can see what will happen to them if they disobey. And what of the probability that other Member-States may think "if Cyprus is out of the Eurozone and can work it out why don't we exit as well?"

It has to be considered though that it is highly unlikely that another country will be in direct need of assistance in the near future (one cannot foresee the outcome of the Italian elections however). This would mean that essentially what the EU would be doing is that they should be supporting one of their own; or even better something they created. Was it not Victor Frankenstein's fault for the monster he had created? Now it is their fault for not looking two steps ahead when they were making the decision on the Greek haircut about a year ago. 

Exits should not be an option for either Eurozone or EU countries. If even a small country the size of Cyprus exits then you may mark the day as the one which set off the destruction of the EU. All that has been built over the past 70 years, all that nations have been through over the past couple of years, with uncertainty and economic misery would be in vain. What is the message by the EU officials if when a nation is in trouble we fail to assist it?

Cyprus is merely an example. Greece was the example in the last few months, and hopefully Italy will not become the next example in the following ones. We cannot have a perfect Member-State, we cannot have a perfect Union. Yet, we can support each other, regardless of petty issues. Spiegel mentions that the island is considered a safe haven for tax fugitives. One can remember posts about Russians moving funds to Cyprus for the last couple of years. Why now? Why didn't the EU try to impose stricter regulations on Cypriot banks earlier than that? 

The same issues arose in Greece, Italy and Spain. Why did Brussels fail to do nothing, not even suggest something when they had known about tax evaders in Greece since 2009 (the now notorious Lagarde list featuring more than 100 names of fraudsters with millions of deposits abroad)? Or why did they not try to change the Italian election law, which essentially does not let the people elect whom they want to lead them? Even better, why haven't they tried to do it when Mario Monti was in charge (he tried to pull it through but I believe that the legislation has not yet been passed) or even try to push Italian politicians now to do it? How about Spain and the horrible situation with evictions and homeless people? 

I can agree that the EU does not have the power to meddle in Member-States legislation and politics; nor should it. Yet, it should be noted that EU law is superior to country law, and thus many a legislation could be passed on in Brussels; legislation on important issues like election law, money laundering or evictions. What is more is that they should be able to impose severe sanctions to the members who disobey on serious issues. Being an optimist I hope that the memorandums have given the EU an opportunity to make the living environment better in the ailing countries than it was before; not used merely for punishment.

Cypriot presidential candidate Nikos Anastasiades with Angela Merkel.
As for a prediction: the EU will grant Cyprus its memorandum and support. How much money the island will receive and what sacrifices they will have to do I cannot know. Yet, it is highly unlikely that they will receive it before the February election results as a change of government will bring a change in credibility; the same issue with Greece over the summer. Just wait and see...

Friday, 11 January 2013

Should the EU bail-out Cyprus?

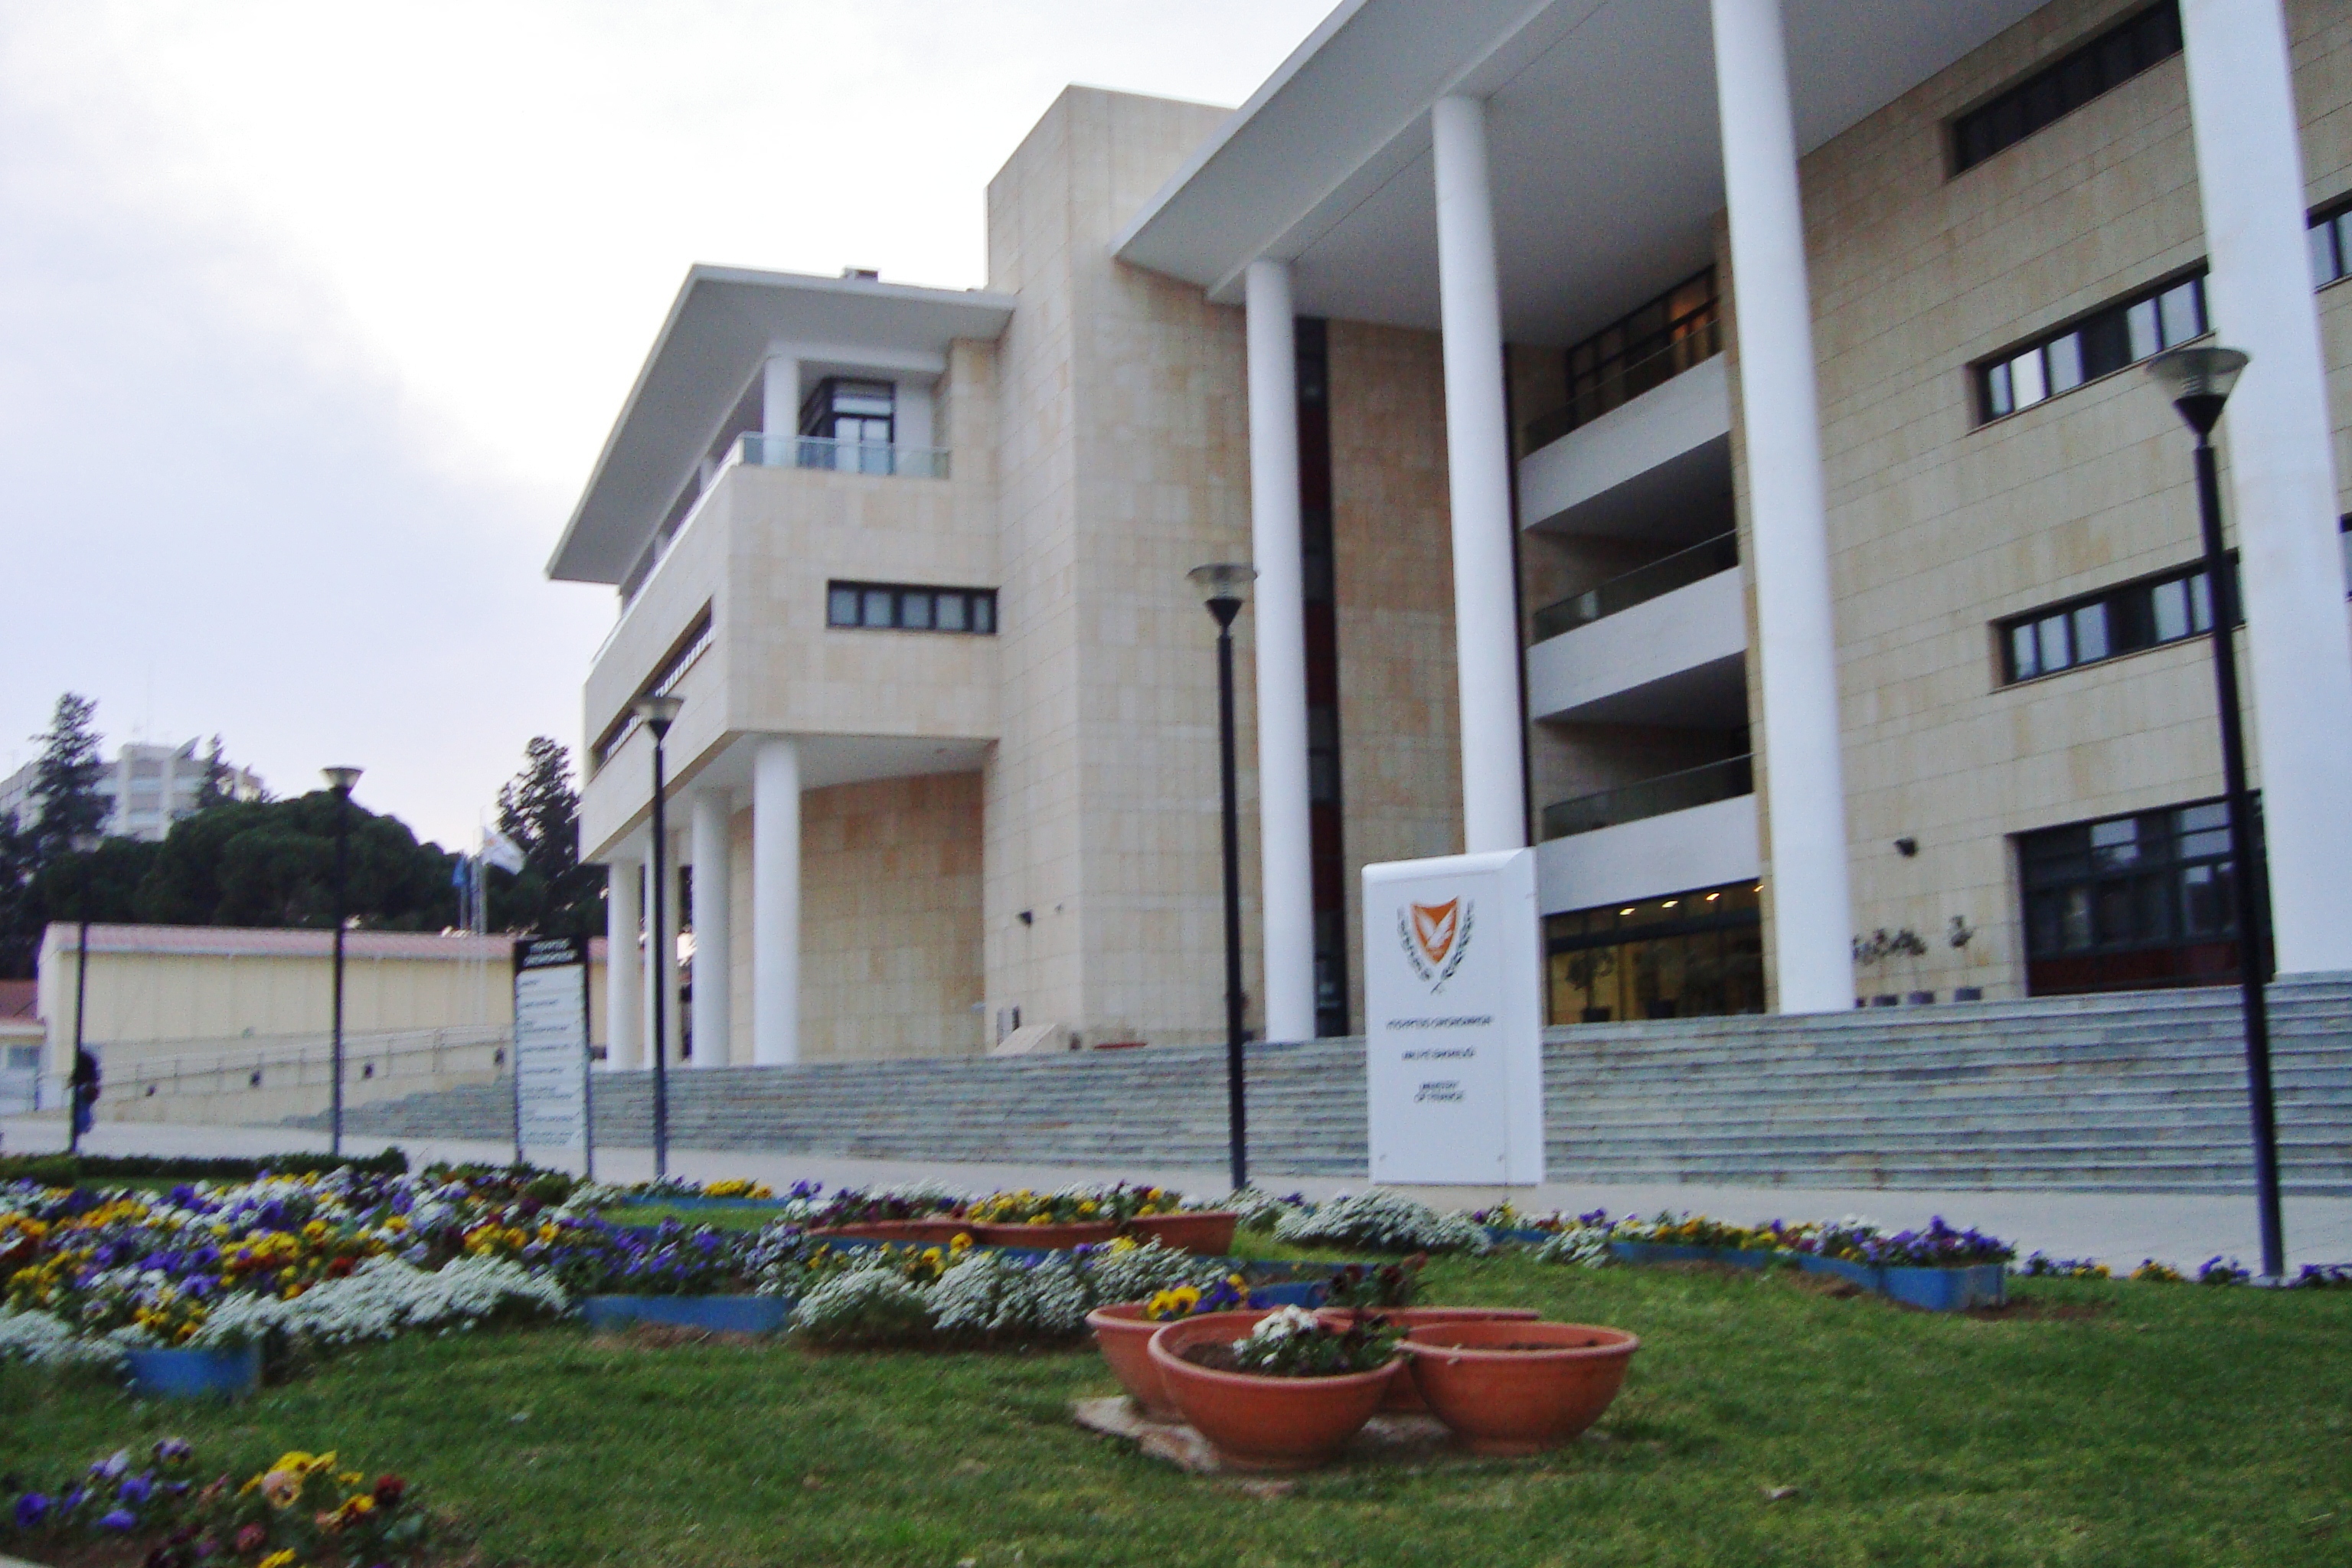
Cyprus Ministry of Finance. Source: Wikimedia Commons
From what I have seen, I was the first blogger to bring attention (on July 28th!) on the worsening situation in Cyprus and the imminent bailout. Media sources have had their reports before that of course but they were largely focused on Greece and the probabilities of a Grexit. Now, it is more than evident that Cyprus is having liquidity issues, largely due to their banks' exposure to Greece (both in sovereign debt as well as private loans). Now, as usual, many media sources have expressed their own views on whether the EU should lend the island money to overcome its difficulties. For example, the Wall Street Journal states that a line has to be drawn and Cyprus should be let to default.

It's always easy to hit the little guy isn't it?

For me, the rationale behind the statement "draw the line" is not very clear. Draw the line where? Let small economies collapse because their effect on the economy will not be as large as the effects of a Greek default? It is the same irrational rationale which has forced the US government to bail-out AIG, Bank of America, General Motors and about 15 other large institutions (for details on the TARP program read here). The message: do not worry if you are large; we shall do anything to save you. Yet if you are small, bankruptcy is your only option. Hmm that doesn't sound very democratic does it?

On the other hand shall we pay €18 billion to a country where the debt-to-GDP ratio is expected to rise over 130-140%? The answer is it depends. First of all the amount is ridiculous. 18 billion is approximately 100% of Cyprus's GDP! (for the calculation have a look at this) It is impossible for a nation to require that much money. Even if they did, the amount could easily come from the ECB's printing machine. Value of euros produced by the EU just in 2012: €184 billion. Cyprus requires less than 10% of that even at the utmost extreme scenario, which again is highly irrational.

Let us take things from the start. Cypriot banks stupidly put more than 50% of their equity in Greek government bonds. Then came the infamous Greek PSI. Had there not been for that, Cypriot banks would not have lost approximately €4 billion's worth of bonds, and they would not have been at the situation they are currently facing. Still one might add, that to the previously mentioned amount of €18 billion, the Troika delegates have calculated about €10 billion for bank recapitalization, and the rest for debt repayment and government needs. Let us examine them one by one.

First, letting the banks collapse should be out of the question. Bank default would cost much more than what it would take for them to recapitalize, even at the extreme scenario of €10 billion. Now let's examine this differently. The island current faces a debt-to-GDP ration of approximately 75% and has a deficit of about 4% of GDP. The latter figure is expected to be reduced to 2.5-3% in 2013 and even further by 2014. This would mean that essentially from 2015 onwards the Cypriot debt will start moving downwards. The issue is what happens until 2015.

What I would propose is in fact very simple. In addition it would only cost around €3 billion. From what I have been reading, Cypriot banks have issued about €1.2 billion in CoCo bonds (for a definition read this). So if they transform these bonds in ordinary shares, their equity base will be significantly strengthened, and they will surely need much less help in finding the necessary capital for them to continue functioning. In addition, another €3 billion should be lent to the Cypriot banks, conditional on the term that they should lend it back to the state to fund its needs. Given that the hole in the banks' balance sheets is about €2.5-3 billion, they would more than cover it with the €4.2 billion influx received, even given that the low ratings Cyprus has received from the ratings agencies. It is highly unlikely that the island would need more than €3 billion for the next year (or even the year after), provided of course that it can roll-over its current debt; which will have no trouble doing given that most of its lays in the hands of Cypriot banks and pension funds. 

In addition, given that Greece is on the verge of a crisis-reversal in 2013, banks would start receiving profits in either 2013 or 2014 from their exposure there, which they could use to directly fund the Cypriot state by 2015. Even if the huge influx of capital due to the gas depositories in the area does not occur, then by a combination of very few austerity measures and an increase in consumption (which will occur if banks influx just a percentage of that €4.2 billion back to the system) the future would be much brighter for the island than any other scenarios. What makes this plan even better is that the EU only has to lend the island about €3 billion, which is essentially nothing to them. Oh, and it can do so by directly funding the banks through the EFSF/ESM funds instead of just having €300 billion sitting around. 

The alternative presents a much darker situation: if Cyprus obtains a loan is excess of €10 billion, then another memorandum and a debt haircut are inevitable. This is not so difficult to see; we have the Greek experiment to indicate that these issues are not so incomprehensible and difficult to forecast as people who are just bored to think two moves ahead may believe. More so, it is their job to do so. (talking about the Cypriot and Irish minister here, who did not veto decisions which were aimed against their countries in two different Eurogroups. As Constantin Gurdigev has commented, their actions resemble the Stockholm Syndrome)

If they are denied of help then the Cypriots have two options: either default and stay in the Union, or exit the Union and avoid default. As forecasts state that there is enough natural gas in deposits near Cyprus to support probably half of Europe, politicians would not risk letting them leave the Union. Yet, Cypriot politicians might actually be too afraid for such a radical solution. These are the odds to which the game is played: the little guy, more often than not succumbs to the will of the big guy, so the latter obtains continuous small profits from their relationship. It is the same rationale with stock market: bets which bring small profits very often when the market seems to be listening to whims of investors. Occasionally though, the market decides it has had enough of them and takes a large fall. What do you think happens to the big guy then?

Thursday, 20 December 2012

The Cypriot Patient

Good news for the Greeks yesterday, as the S&P ratings agency has upgraded the nation by six notches, from "Selective Default" to a "B-", with a stable outlook. Hopefully, the agency can understand the situation better than everyone else, and the Greeks will be able to say that they have put the worst behind them as 2013 leaves. Yet, their neighbouring Cyprus now appears to have taken a harder hit than first expected: the approximate bail-out package just for bank recapitalization is expected to be about €10 billion, the second largest in history, measured as a percentage to GDP.

Newspaper cover from Cyprus. Source: cyprusgasnews.com
Data for the second quarter of 2012 have shown that so far the island has a 74.6% debt-to-GDP ratio, or approximately €13.2 billion (simple calculations can show that Cyprus's GDP is about €17.7 billion). If we just add the €10 billion to receive the amount would reach a staggering 130% debt-to-GDP ratio, or €23.2 billion. Although I cannot find the article now, I remember a Cypriot authority stating that the debt burden would not exceed 120% (or at least that's what he hoped for), a threshold over which debt is not considered viable any more. It would appear that this was just wishful thinking.

The interest rate for the €10 billion bailout is expected to be around 2.5%, as Finance Minister Vassos Shiarly expects. Although I would like to know where he got those expectations from, even if he is right, an island whose budget is around €9.5 billion, would have to pay about €250 million per year just on interest payments.

Is this sustainable then? The answer is it will depend on how the Cypriot economy will react to the fiscal adjustments (aka austerity measures) the government in association with the Troika has pushed through. The expected adjustment will reach 7.25% of GDP. Assuming that GDP only declines by 3.5% as expected, it would mean that the debt-to-GDP ratio will increase by more than 5%. Oh, and the careful reader will also note that in the above calculations the amount paid for debt refinancing and other government needs has not been added. Guess how the calculation for sustainability goes when another €6 billion is added on the tap. Yes, exactly like Greece's.

What many have not yet realized is that although bad spending policies by the government and bad decisions from the banks have worsened the problem in Cyprus, another culprit has to be the Eurogroup itself. Had the infamous decision for cutting Greek debt by 70% not been taken, the Cypriot banks would not have lost around €4 billion of hard-earned money. Instead, they are now eager to receive government support or they will have to be liquidated. (for more details on who to blame for the crisis read this).

Obviously, one would be insane not to assign blame to the politicians or the bankers, who have tolerated and promoted a policy of over-spending and over-lending for years. An asset bubble had been raging for years in the island, assisted by the bankers, land developers and foreign demand. Now that the time for things to go back to normal has finally come, people naturally hate it. Living in fantasy for too long will cause you to forget what reality really is. It appears that everyone seems to forget that a correction was bound to happen some time. For Cyprus, this time is now. Nevertheless, consequences would have been much easier had the Eurogroup not taken that decision. Not just for Cyprus but for the rest of Europe as well.

Nevertheless, Cyprus can feel that it has been treated unfair for two reasons:
1. The aforementioned Eurogroup decision has brought the crisis much faster than the economy expected it.
2. The Cypriot banks are not getting funded by the ESFM/ESM funds like Spain's but are forcing the government to assume responsibility for them.

Even if we accept that Cyprus had opted for a bail-out before Spain did, it would still appear that the EU has a strange way of operating the ESM: not depending on the bank or its significance in the local economy, but on a sovereign level. If a nation is more important than another, economic-wise, then it would appear that they will support it and let the other fall. Yet, this is not the solidarity the EU officials have been proclaiming and surely not the preservation of peace and equality, values for which it received the Nobel price earlier this month.

This sort of injustice sets a paradigm for the EU authorities: they operate exactly like national governments do: assist people in power, those who are economically strong or have good connections and do not pay much attention to "ordinary" people. They just do it on a wider scale. Is this the kind of governance that we should be happy about, or is this how the first visionaries saw the EU becoming? I would certainly hope not.

As for the sustainability of the Cypriot debt, it looks that history will be repeating itself: Greece and now Cyprus. A €16 billion package will not be enough if the banks are not directly funded by the ESM/EFSF. New memorandum will have to be signed soon, and debt reliefs will be implemented.

That is, unless they bring their minds about and decide to do what would really make the island's transition from recession to recovery easier. Otherwise, it would be recession to depression.

Friday, 2 November 2012

Strange Tactics

To my (and I think everyone's) surprise, yesterday German Finance Minister Wolfgang Schäuble, has stated that he does not expect concrete negotiations between Cyprus and international lenders to start before 2013, suggesting that the island has missed a November 12 deadline and could be at risk of running out of money before the end of the year. In addition, the Cypriot are now fearing that Troika will enforce an increase in the tax rate for businesses, which is now at an attractive 10%. What ever happened to your supporting the Eurozone Wolfgang?

It seems that Schäuble's comments where not the only strange stories on the news. Having heard the estimates for the financial aid Cyprus will need to overcome the current situation I was struck with amazement: Troika suggests a €12 billion pack for the two large Cypriot banks (Bank of Cyprus and Popular Bank) and an additional €5 billion for government needs. If one has a look at the balance sheets of those two companies (you can find them here for the Bank of Cyprus and here for the Popular Bank) the total number of loans of both banks combined does not exceed €50 billion. (To be fair the amount is about €46 billion, nevertheless I will be kind to Troika and round it up to 50). Thus we have: €50 billion in loan portfolio and €12 billion in aid, which means, hmm that essentially 24% of ALL loans given out by the two banks are considered as non-performing.

Really? 24%? How on earth could these banks have survived so far? Were they using nothing as collateral? If the numbers are true, then it would be better to incarcerate all of the top management of both banks, and all officers of the regulatory authority. Nevertheless, if those numbers were true, the banks should have been declared insolvent a long time ago. If one every 4 loans is non-performing I cannot see how a bank could have survived. However, to the extent of my knowledge, (and in accordance to their financial statements) both banks are still functioning and are still profitable.

Source: politico.ie

I do not know how the Troikans have reached these conclusions but they hardly seem plausible. Negotiations seem to reach an impasse on the amount of assistance the island needs. The Cypriot government says €6 billion, Troika insists on €12 billion. I think this is the first time in history when the receiver of the loan states that he does not need more and the loan giver insists on him taking some more. (then again a resemblance with the sub-prime lending policies in the US does come in mind...). Imagine it happening in a bank:

Client: Can I have a €10.000 loan?
Bank Officer: I think you should have a €20.000 one. It is better for you.
Client: But I believe that €10.000 would be sufficient, and besides I would have trouble repaying any larger amount.
Bank Officer: Still, I think that you should take the €20.000.

Thank God the IMF is not a regular bank or we would be bailing them out every now and then. 

Wednesday, 3 October 2012

New Regulations for Old Sins

I do not know neither Michel Barnier nor Erkki Liikanen (the European Commissioner for Internal Market and Services and the governor of the Central Bank of Finland respectively), nevertheless I quite like their proposals. Here's what the latter's report stated:
"The group has concluded that it is necessary to require legal separation of certain particularly risky financial activities from deposit-taking banks within the banking group. The activities to be separated would include proprietary trading of securities and derivatives, and certain other activities closely linked with securities and derivatives markets."

I do not know how bankers may feel about this, yet still I believe its a good idea. Not so radical and effective as breaking up the banks into independent entities, but still good. What their proposal would do, is to "safeguard" depositors from banks which are willing to invest in forms of investment banking activities and not just the deposit-and-loan model. This would mean that both states and depositors are safer against any trades which end up bad. (You may ask the now bankrupted Barings Bank, once the greatest bank in the world, what may happen when a trader does something foolish. For a more recent example have a look at Société Générale's losses due a single trader's mistake last year)

Although, to be fair, it was not the traders who caused the 2008 sub-prime lending crisis. It was the banks themselves. Through debt securitization, banks are allowed to lend much more capital than they currently have. (for further details on how this works have a look at this). This would mean that they are more susceptible to prices of the assets they use as collateral than they were before.

The expert committee has also recommended that property lending should be underpinned with larger capital reserves than now and executives should receive part of their bonuses in the form of bonds to ensure that they contribute to any bailout of their bank. What would be even better is a solution Warren Buffett has proposed: No bonuses at all, just loans to the executives to buy ordinary shares. This would tie the executives to their firms, knowing that if the bank prospers they will prosper as well. 

On a different note, Mario Draghi is fighting a growing opposition (notably from the German side) about his OMT plan. Concerns about the feasibility or legality of such a move have been raging since the announcement. (For a review of Draghi's responses and his competitors' comments Der Spiegel has a very interesting article, found here). As for myself, I do believe that the longer we may go without using any of these plans, the better. Time allows economies to move from one end of the cycle to another. Yeah, fine, it may also be the case that they stay where they were or become even worse, but still, this does not seem to be the case with any nation in the EU (maybe except Spain). Although things appear bad now, they will be slightly better in 2013 for most countries (again here I exclude Spain and now Cyprus). Let's hope that Draghi will not have to use his guns to safeguard the Union.

P.S. On the Spiegel article mentioned above I read that people in Germany have a fond memory of the mark. No kidding! I bet the Spanish remember the peseta and the Italians the lira with a certain degree of fondness. And would someone guess why? Well, simply because things were better than they are now before the introduction of the Euro in both Germany and the South. Or at least that's how they remember them to be! They were not reminiscent of the mark 3 years ago when everything was fine.

Thursday, 20 September 2012

Extending vs Haircutting the Greeks

Although today has been heralded as the day when the Greek government and Troika would reach an agreement on the new austerity measures and reforms, don't hold your breath. While the Greeks are waiting to see how many benefits will be cut and how much will salaries and pensions will be reduced, for the rest of the world, hope is that with this package, voices claiming a future Grexit will quiet down. 

On the subject, David Riley, a director at Fitch Ratings, has stated that "An agreement on any change to the Greek program before the next EU summit in October would reduce the risk of a Greek exit or second default". He has also stated that the resolution of the crisis will not be quick and that any positive development would support Fitch's view that the Eurozone would survive. Oh the support! It seems just like yesterday when most rating agencies had their money on the Eurozone failing (or was it a month ago? I wonder what John Paulson and George Soros are betting on now).

Truth is, Fitch is right. The Eurocrisis is not over and it will be quite long until its over. Although I am not good at predictions, I think that 2013 will not be a great year as well, however, still better than 2012 for most nations (with the exception of Cyprus and probably Spain. The biggest question is what will happen to France and Germany). I would like to agree with predictions that 2014 will bring growth back to the Union, nevertheless, I would prefer to refrain from it for the time being. Time will tell. If the Greek austerity-and-reform package is granted an extension then the EU will be a much quieter place in 2013. What remains to be seen is what kind of "magic" will Mario Monti and Mariano Rajoy will do in Italy and Spain respectively to prevent their economies from blowing up.

The CEO of Commerzbank, Martin Blessing, has said that another Greek debt haircut is eminent. What exactly are they going to cut? Banks are now going to receive about 21 cents for each euro they have invested in Greece and this has been the main cause for financial turmoil in Europe. If a even if another 30% haircut is implemented then banks will receive 15 cents for each euro invested. If that does not wreck more havoc in the already trembling South economies then nothing will ever will. Bank applications for bail-outs will soar and the ESM will put its newly printed money into good use if a new Greek haircut is promoted. So, thanks Martin but keep the Blessing for yourself. (as a note, Commerzbank has no exposure to Greek debt, so the CEO might feel a bit free do say what he pleases on the subject)

Extending the period of restructuring in Greece would be a much better alternative than a new haircut, especially for Cypriot, Italian and Spanish banks. If changes are implemented in a longer horizon then GDP will not contract as much (maybe even at all if the reforms are gradual) which would mean that debt, as a percentage of GDP, will be reduced in the future, thus making it more sustainable.

Wednesday, 29 August 2012

Bank Bailouts: The Correct Way

Some time ago, a book I read stated that the very nature of capitalism was to allow firms to die without any consequences to the system. The author wondered why the same thing isn't possible with banking institutions. That author was Nassim Nicolas Taleb and the book was titled Black Swan. (However, I wouldn't really recommend the book) Although at first I thought the author was right, after considering it I realized that the banks are not at all like any other firm.

If tomorrow Google were to file for bankruptcy, the consequences would be a lack of a good search engine and thousands of Google employees left without a job (and you wouldn't be reading this!). Otherwise, no harm would be done to the ordinary person. Now imagine what would happen if one of the major banks were to collapse: millions of people would suddenly be worried of being left with little or no money (although a country guarantees approximately 100,000 euros of deposits by each person in each bank). In the end, people would get their savings back (expect the persons which had amassed millions who will only get 100,000), however, the whole procedure would be traumatic to the ones who were unlucky enough to get caught in it. Nevertheless, such a procedure is preferred to the cost of pumping a bank with new money every now and then just to sustain it.

Thus, the question becomes: When should banking institutions be rescued? The answer is simple, although it may be tricky to define at times: When they are solvent, largely problem-free and have faced trouble only as a result of an unpredictable event to which they bore minimal or no responsibility. This, for example, would be the case with most EU banks which suffered great losses from the Greek haircut (although there were other banks which had overextended credit over the years).

If a banking institution is thought to be worthy of rescue then the course of action should be by directly providing liquidity to them. This would mean that governments, Central Banks or (preferably) an institution like the ESM, should provide liquidity to the banks; with the latter issuing new shares with voting rights, committing to repurchase them at an amount obtained after accounting for a fixed interest rate, and agreeing that the institution's participation in the bank's equity capital would be reduced each year, thus making sure that the stream of payments from the bank to the state would be continuous. Even if government (or Central Bank) intervention in banking institutions is not considered a good thing, it is much better than merely purchasing preferred shares, as the very recent Barclay's example indicates. By agreeing to pay interest on the amount given to them and repurchasing those shares at fixed intervals, it is assured that the taxpayers' money is not just thrown down a bottomless pit, making the banks more careful in their future investments and gradually reducing government intervention within them.

Following this, the distressed bank should implement some austerity measures, either by cutting down salaries or other benefits or, better, by reducing its activities both at domestic as well as at an international level. Needless to say, the bank's heads at the time of government intervention should be replaced. The bank could spin-off some of its operations if they are profitable, however, this should be done in a way that the new company is an independent one and not with the bank still controlling a substantial interest in it. Likewise, the spin-off should not be sold to another bank as this would increase the other bank's risk of becoming too-big-to-fail.

In the case of the bank becoming insolvent, problem-ridden with issues which are not due to unexpected events (e.g. management issues, poor lending decisions, etc) then it should be let collapse just like any other ordinary firm. If the bank has some operations which are profitable and well-functioning, then these should be spun-off, or sold to another company, even though selling them to another bank should be avoided for reasons of the other bank becoming extremely large. What the reader may inquire is what if the second bank is already too big? What difference would it make if the profitable operation is sold to them? First of all, a new spin-off will require more employees (think of new management, trainees, secretaries, even cleaners) than if it is sold to another company where existing economies of scale would take over. This would have a positive effect on unemployment especially since other bank's employees are expected to be laid off as a result of the collapse. Then, even the acquiring bank is already too big, in what scenario would the government (or another institution) be spending less for stabilization: saving a 100 billion bank or a 105 billion bank? And remember that's billion...

Under the current scheme, most banks are either classified as too big to fail or too little to have any exposure. Take the UK for example where only 5 independent large banks exist, with the government having interest in two of them. What should have been done was to reduce the level of activities of the Royal Bank of Scotland and Lloyds Banking Group to levels where such intervention would be easier in the future, also allowing the creation of more banking institutions, which would promote a competitive environment instead of an oligopolistic one.

Thursday, 16 August 2012

Greek Bankruptcy can help the EU?

In an article in Der Spiegel yesterday, Stefan Kaisser states that a Greek bankruptcy, although costly, is the best way to resolve the current situation in the EU. Current plans for Greece, as stated in the article, are the following: The Greek government is supposed to borrow the money it needs from the ailing Greek banks. In return, the banks receive sovereign bonds that they can, in turn, provide as securities for new loans from Greece's central bank. In this way, Greece's central bank is financing the Greek state in what is really just a kind of shell game that gets riskier the longer it is played. This arrangement reminds me of leveraging (the idea that instead of banks lending a proportion of what they have as deposits, they end up lending maybe 50 times more, a policy most large banking institutions adhere to) and is not one which leads to stability.

However, I do not believe that bankrupting Greece would solve anything.

On one hand, the consequences are unknown. Even Germany, with its strong economy, has to to prepare itself for a major economic catastrophe. And whilst the Germans may have the funds to bail-out their banks, most EU countries do not. So what would happen is that more countries will ask for help from the EFSF/ESM. What happens if these countries also face fiscal difficulties which would be a direct outcome of the Greek bankruptcy (and in essence German EU politics)? Let them go broke too?

The other big question is what happens after the bankruptcy. Does Greece go back to drachma or does it stay in the common currency? If Greece exits the euro then what is the message sent to other countries: bad fiscal planning and you are out of the euro? Will Greece be allowed to return after some years have passed? For conversation's sake let's assume that Greece does not do the stupid thing and remains in the Euro (although I highly doubt it, since anti-european movements will increase in popularity after a bankruptcy). What happens next? Who is going to lend a country which received enormous amounts of help from the ECB and the IMF and still managed to default? Guess: the ECB and the IMF again.

Although the Greeks should - and do - receive the blame for the situation in their country, Merkel's austerity remedies seem to have lost their charm since they have not been able to reverse the current situation. The Greeks themselves cannot do anything more than austerity measures and stimulus from the ECB anymore. What should be done is a change in German and EU politics: The ECB should be allowed to move directly and INDEPENDENTLY in order to buy Greek bonds or any other sovereign bonds deems proper, to restore order in the markets, just as a normal central bank would do.

Let us not forget that it is the Greek haircut we have to condemn for the current situation in the EU; and this is a direct consequence of political decisions (mostly German) which were based on flawed arguments. I do not think that it is too late for an ECB intervention which would end problems in the South in the next years and restore confidence in the markets.

As for the "spiral of threats and rescue actions" Berlin and Brussels got themselves into they only have to accuse themselves. It is never too late for admitting a mistake and moving on to correct it.

Sunday, 12 August 2012

Economists and the Real-Life Economy

Every time a crash, or a crisis or recession or any bad news in general comes up, people run to economists to "help" them "understand" what has happened. What most people fail to understand is that, about 99% of economists have no idea what is happening in the real world. The reason is simple: they are so caught up in their studying, publishing articles, using advanced mathematics and statistics to impress other economists with their knowledge that they do not actually know, let alone understand, about what goes on in the real world. 

Thus, their knowledge is purely theoretical. Even what economists call empirical work (i.e. something which actually uses observed data instead of pure mathematical theories) is in fact a manipulation of past data, under statistical tools, to reach a certain point. Very few can leave the stagnant traditional economic thinking and start to think on their own. If one remembers, in a scene of Bryan Singer's Usual Suspects, Kevin Spacey states: "The greatest trick the Devil ever pulled was convincing the world he didn't exist.". In the same context, the greatest trick economists ever pulled was convincing the world that they understood economics.

The worst outcomes of this "misunderstanding" are that:
1. Economists with no idea on how the real world operates are appointed in critical positions in the economy
2. Good economists are mistakenly thought as bad ones, a consequence of bias and prejudices (obviously, if you ask an economist whether he belongs to the 99% or the 1% of economists s/he will  always say he belongs to the 1%)

This situation is described in Esther Dulfo's and Abhijit Banerjee's book, titled Poor Economics. They talk about a situation named the 3 I's: Ideology, Ignorance, Inertia. Although the authors (which I believe deserve to be at the 1% we have talked about earlier) mostly use it in describing politics and policies in third world countries, this situation is more than evident both in the EU as well as the world economy.

People with an ideology try to promote changes or policies (either for better or for worse) and the policies seem to fail, mainly due to their ignorance on the subject, as they are watching it from a distance. The situation, does is not made better due to inertia, i.e. people's "apathy" towards a policy which in essence does nothing.

The same rationale holds for the Greek bailout: economists and policymakers decided that a haircut of 70% of the bonds' value and severe austerity measures should be great to fix the problem. Well, I guess the situation looks better and decisions are easier when its not your job, city or country on the line. Or is it now?

Monday, 30 July 2012

An Alternative to the Greek Bailout

Don't know if you heard it but EU officials state that they plan to do another, smaller haircut to Greek bonds to make the debt level fall to about 100% of GDP thus theoretically making it more viable. This makes us understand the reasoning behind EU policymakers decisions: If one mistake doesn't fix things why not try two? Well gee guys did you have to do a PhD to learn that?

Without a doubt the Greek haircut was a mistake. All it did was make the banking system more fragile than it already was (let us not forget that it had already faced a sub-prime lending crisis which had barely finished when this started) and countries who thought had no financial problems turn to the ECB and the IMF for funding to rescue their banks. Another stupid idea is as I have mentioned in a previous article using the IMF to fund European countries. If the ECB will not act as a normal central bank then why bother with the Union and the common currency? Just make trade agreements and return to national currencies. Either we become the United States of Europe or we shut this thing up before it blows in our faces. But I am getting out of subject.

As usual, my friend Wolfgang (whom you have met here) will ask what alternative I would propose for the Greek Debt. Which is simple. Make a separate entity, like for example the EFSF, and let it buy all Greek debt. Since the entity will be funded by the ECB it will have no liquidity problems as the Greeks will slowly (as if now they are really fast in repaying it right Wolfgang?) repay their debt. The entity would control the old bonds and slowly repay the banks as the flow of cash increases with a flat interest rate for all bonds. The banks' Greek bonds would have been held in the entity without them being able to sell or otherwise use them; however this would be much better than taking losses of tens of billions of euros over a year. Ask any bank in Spain. Italy, Cyprus or Greece if you don't believe me!

What about refinancing then? Well here the idea would have remained the same. The country would have to go through severe structural changes, cuts in government spending, etc etc and the refinancing would be made by the ECB. This way the only country that would have been "punished" would have been the one which made the mistakes who led it there.

Had this occurred we wouldn't be talking about banking problems in almost any country. The only countries which might have faced that would have been Greece and Cyprus. If the banking sector problems had not occurred then the rating agencies would not have degraded most of the countries they had. Thus, with only some budget cuts the Eurozone would have been a happier place.

P.S. OK Wolfgang I admit it. The above plan has a caveat: It would essentially mean that Silvio Berlusconi (you remember him right? The bunga bunga guy!) would have remained in power. Oh well, I guess we would have to live with it. (Sorry Angela!)

Saturday, 28 July 2012

Cyprus Bailout and Austerity Measures

Having written an opinion on austerity measures in South Europe I think it is time to focus on the current problems faced by Cyprus. Although its government states that it has money to hold until September (other sources state that it has money to make it until the end of the year) it is common knowledge that the island is bankrupt. For more information on the situation read this article by Wolf Richter where the nation's current situation is outlined. Prospects appear as dark as they can get while the Troikans believe that the island will need about 10 billion euros to cover it's needs (both for the fragile banking system as well as for a black hole in it's finances). 

The Cypriot government is headed by a President whose communist views have spurred controversy even amongst its European Allies and who seems unable to commit to actions that will alter the situation. The only moves that have been made towards fixing public finances were done in September and December 2011, by a Finance Minister (Kikis Kazamias) who resigned in March stating "medical reasons". However, the Cypriot President, Demetris Christofias, despite his growing unpopularity even amongst its own party, has requested that the structural changes that need to be done in the Cypriot economy should span over the next 6 years and not over the next one.

For once, I do believe he has the right idea, although for the wrong reasons. His reasons are strictly political as he must think, and many others in his place would have thought the same, that the effect of strict fiscal discipline will be devastating for the future of his party. With elections coming on February 2013 he has every reason to be worried. (However, I don't think that this will do much more harm to his reputation than he has already caused to himself by his inability to face reality).

My reasons are strictly economic. Changing fiscal policy so rapidly will cause a wave of new issues to the already problem-ridden island. Cyprus has one of the highest private debt ratios in the world of about 300% of the GDP. Add to that an exposure of about 40% of the Cypriot banks' loan portfolio to Greece and an economic confidence level at its lowest since they have started compiling one, and you get an explosive package. So, if one may ask, what happens when to a country with a 300% of GDP private debt when fiscal policy is abruptly tightened without an expansion of credit? Well, I guess (the troikans can verify this if they can) that foreclosures, bankruptcies, a confidence level even lower and unemployment levels reaching 15-20%  are the logical consequences. After that, you can understand that the next victims are the banks themselves.

Cyprus Popular Bank, the second largest bank on the island has led already agreed with 185 employees on a "voluntary" retirement scheme. This would help it fulfill a target of reducing employees by 7% this year. The rapid and rather stupid expansion of Cypriot banks in both Cyprus (Bank of Cyprus, the leading bank of the island has about 120 branches in a nation where the total area is less than 6,000 square kilometers. The same numbers more or less hold for Laiki Bank. However the exaggerations in both banking and fiscal policies must not be revoked immediately as this would not bring the island to the brink of destruction - it will push it over the cliff.

If the austerity measures are pursued with severity and results are expected from the first year of imposition the island will need another group of Troikans until next year to hand over several billion more to save them.