Showing posts with label bail out. Show all posts

Friday, 3 January 2014

Spain's "Sucess"

Big news this week was that the ESM had successfully ended the support towards Spanish banks, a story which came in addition to the already positive outlook for the country. In the words of the Spanish Finance Minister "2014 will see the net creation of jobs, higher even than we predicted in September in the budget, and the jobless rate will fall". The ESM has also provided us with a list of the positive developments in Spain which made it possible for it to exit:
1. Bank restructuring is well underway.
2. Transfer of impaired assets to an asset management company (SAREB, i.e. a "bad bank") has been completed.
3. Steady reduction of Eurosystem funding.
4. Positive banking results in 2013.
5. Markets acknowledging Spain's progress.

While these are all good news, there are still many problems which have been kept hidden under the carpet. First of all, we 'll start with the infamous unemployment rate, currently at the staggering 26.7%, meaning that more than one out of 4 people in Spain is unemployed. Add to that an astonishing 56.1% of youth unemployment and you get a much better picture of how things are doing in the country. Oh, wait there's more: 7.1% of the labour force in the second quarter of 2013 was just working part-time, brining the percentage of the people working full time is just 66.2% of the population.
What does high unemployment indicate*? Since people tend to consume out of income, it means less consumption. The trend has been obvious in Spain over the past years:
With less consumption, firms will be facing more trouble than before, with the trend of new orders and firm bankruptcies continuing:
Don't let the decrease in Q3 bankruptcies fool you: remember that the Spanish economy is highly seasonal (as are most of the periphery countries, especially those with a large inflow of tourists) and as restructuring specialists commented "2013 is going to be the year with the most bankruptcy filings in Spain's history, without any doubt".

All of the above have important consequences to the health of the banking system: overall Bad Loan ratio climbed to 12.7% in September 2013 compared to 12.1% in August, while the severe deleveraging of the banks' balance sheets continues as we speak. The ESM focuses on the positives, yet the problem is that they use just Q2 data, which allows them to focus on what they like. For example, in Q2 industrial production rose by 0.8%, making some very happy. Yet, the Q3 data show that the increase was not permanent:
One cannot be certain of how Spain will fare in 2014, yet the popular opinion (and the one shared by yours truly) is that the coming year will be better than 2013. This has also been shared by the market: with the danger for a Spanish or an Italian default reduced, bond yields have decreased over time. Yet, whether the over-optimistic estimations of the Spanish Finance Minister will occur is something which is really doubtful. For significant growth, we need stabilization and Spain has unfortunately not yet stabilized.


The fact that the ESM stopped its backing of the Spanish economy is rather irrelevant to the stabilization of her economy: the credit provided was just the amount needed for her banks to continue functioning and nothing more. The Spanish authorities have agreed to exiting the ESM based on the fact that the worse is over. We agree on that; but it doesn't mean that the situation will get better. If anything, optimists would expect the situation to stabilize over 2014, with some quarter-to-quarter growth after the stabilization as the austerity-based new budget, with more cuts in spending and more wage-freezing for public servants. The country's increased exports make it more prone to external shocks and the payments for the debt assumed in order to revive the banks will drive policy for some years to come.

So, ESM, let's be realistic: Spain is anything but stable. Don't focus on just the positives and please give out up-to-date data. 2014 will be good for stabilizing the economy and some slight growth if the increased austerity does not cause more harm in the end. Everything else is just wishful thinking.

*Some argue that unemployment fell in December 2013. The problem is that the hires were highly seasonal and in addition, the Spanish labour force appears to be shrinking as Euronews reports. Thus, the good news are nothing but the absence of bad ones

Monday, 21 January 2013

Banks, Audits and Ratings

Most of the readers who are watching the current developments in economics and banking have surely seen the case of Deutsche Bank and Banca Monte dei Paschi di Siena SpA. For those who did not what the German bank did was to create a complex derivative which was able to hide all the losses its Italian counterpart had, with the latter placing a losing bet on Italy's government bonds (for further details, Bloomberg has an excellent article on the subject). 

The point to be made in this article is beyond the complex derivatives world where many of the sold products cannot be understood even by those who created them. It is about the role of banks in modern societies and the much more important role of auditors and rating agencies who supposedly examine these accounts thoroughly to provide investors with their opinion on the subject.

Auditors have long been in my mind (or maybe in everyone's mind) as the people who oversee whether a company is doing it's job correctly in informing investors and the general public over its financial position and the dangers it might face in the future. Yet, as many have stated over time, there seems to be a great conflict of interest: auditing firms get paid by the people whom they audit. So the situation presented to them is similar to the following example: company X is paying you a substantial amount of money every year to tell everyone else in the world if its practices are correct and whether they should be fine in investing with it. Yet, if investors do not put their money with company X as a result of your operations, then the company will seek another auditor and you will not get any money. Morally there should be no problem: you do your work and be honest on whether the company has a solid financial position or not. Yet, as most things in real life, it is not just black or white. What happens if that company is very large, probably your best client, have a long professional relationship with it and is one of the major sources of income for you? If you disclose the truth you lose a very large income which you were most likely going to have for the rest of that company's life. If you do not then you may face consequences. Not so easy is it?
The accounting cycle. Source: Wikimedia Commons. Author: Club-oracle
Yet, it should be. Remember the failed energy giant Enron? Well Arthur Andersen, the firm who performed the audits for Enron was shut down after the scandal. What is more, the Andersen's auditors were not even allowed to work in the industry again. Now do tell me if that happened every time when auditors did their work bad, how many auditors would we have? Either very few behaving well or many behaving well. Given the workings of the supply and demand forces I think the latter is much more probable than the former. Yet, as people do not get punished for their wrongdoings much of this is continued. Had the auditors who reviewed the Greek banks' accounts in 2008-2009 posed any thoughts on the quality of their loans or their financial positions? How about Spanish, Italian or Cypriot banks? Had the auditors done their job correctly in Germany or not? 

One may argue that the banks' financial accounts are more complex than any other company's. Maybe that is so. Yet, as the student's expertise rises should the examiner's expertise rise as well? If these people are not really experts in their fields (i.e. bank auditing) what business do they have reviewing balance sheets?

A similar point of view arises when one looks at the ratings agencies. Over the past few years many have questioned both the legitimacy and the trust people should have on ratings agencies (for a detailed post on the subject I refer you to Protesilaos's post here). Yet, nations and individual companies watch them eagerly as the opinion of Moody's, Fitch, and Standard&Poor's shapes the markets in most (if not all) countries of the world. They are considered independent and yet their source of income is derived mainly through the same channels as the auditors: the company who wishes the agency to rate a product (or the whole company) pays them a significant fee to do so.

Although many might argue that they are indeed honest with their prediction on sovereign nations over the past couple of years (at least in Europe) I would remind the reader of the sub-prime debt fiasco. While these collateralized products should have been graded as poor investments they had been awarded an AAA status, the highest obtainable in their scales. Maybe they could not have seen what would happen. Or maybe knowing that if they impose harsh ratings they would be losing clients to the other two each decided to be lenient with their ratings. Very lenient if you consider the chaos that occurred in 2008...

What can we do about this then? Should we use more and more experts to oversee that banks are doing their best not to "cheat" investors? Should we impose stricter rules on auditors and rating agencies and the problem will immediately be solved? The answer is actually much simpler than most people believe: regulations which would forbid banking institutions from using derivatives other than for currency and interest rate hedging (the reason is that currency hedging has good reasoning behind it as it protects the bank from severe changes in the exchange rates. Similarly for the interest rate hedging) would solve the problem much better and much faster than anything else. If banks are not allowed to invest in complex derivatives or buy loans from other banks then this would both make the banks' and the auditors' work easier. In addition it would have the advantage of the banks being less prone to bubbles and busts. Which would mean that less government support (i.e. tax-payers money) will be needed to bail them out.

What should happen is that banking institutions should be completely independent of all investing activities other than the ones described above. The banking industry should make a return to the traditional commercial bank model instead of the do-it-all one it is currently practicing. Sure, profits will be reduced. Still the world would be a much better place. Banks have outgrown most of their home nations. Even in Germany, Deutsche Bank's assets are about 2/3 of the German GDP. You may only imagine what happens when other banks are added. Deutsche was one of the main orchestrators of the 2008 financial crisis by issuing tremendous amounts of collateralized debt obligations and selling them to investors. It is claimed that they have failed to acknowledge a up to $12bn of paper losses in their $130 billion portfolio of leveraged trades. You may imagine the assistance needed when if this bank ever needs assistance. Yet no actions of forbidding it from trading and forcing it to stick to its commercial activities has been taken...

We can only safeguard ourselves and our banks by making them less prone to collapse. That can be easily made by forbidding them to engage in investing activities, imposing harsher penalties to misbehaving auditors and ratings agencies. Still, nothing has been done. Let's hope that legislators decide to take some action and refrain from the "this time it's different" notions...

Friday, 11 January 2013

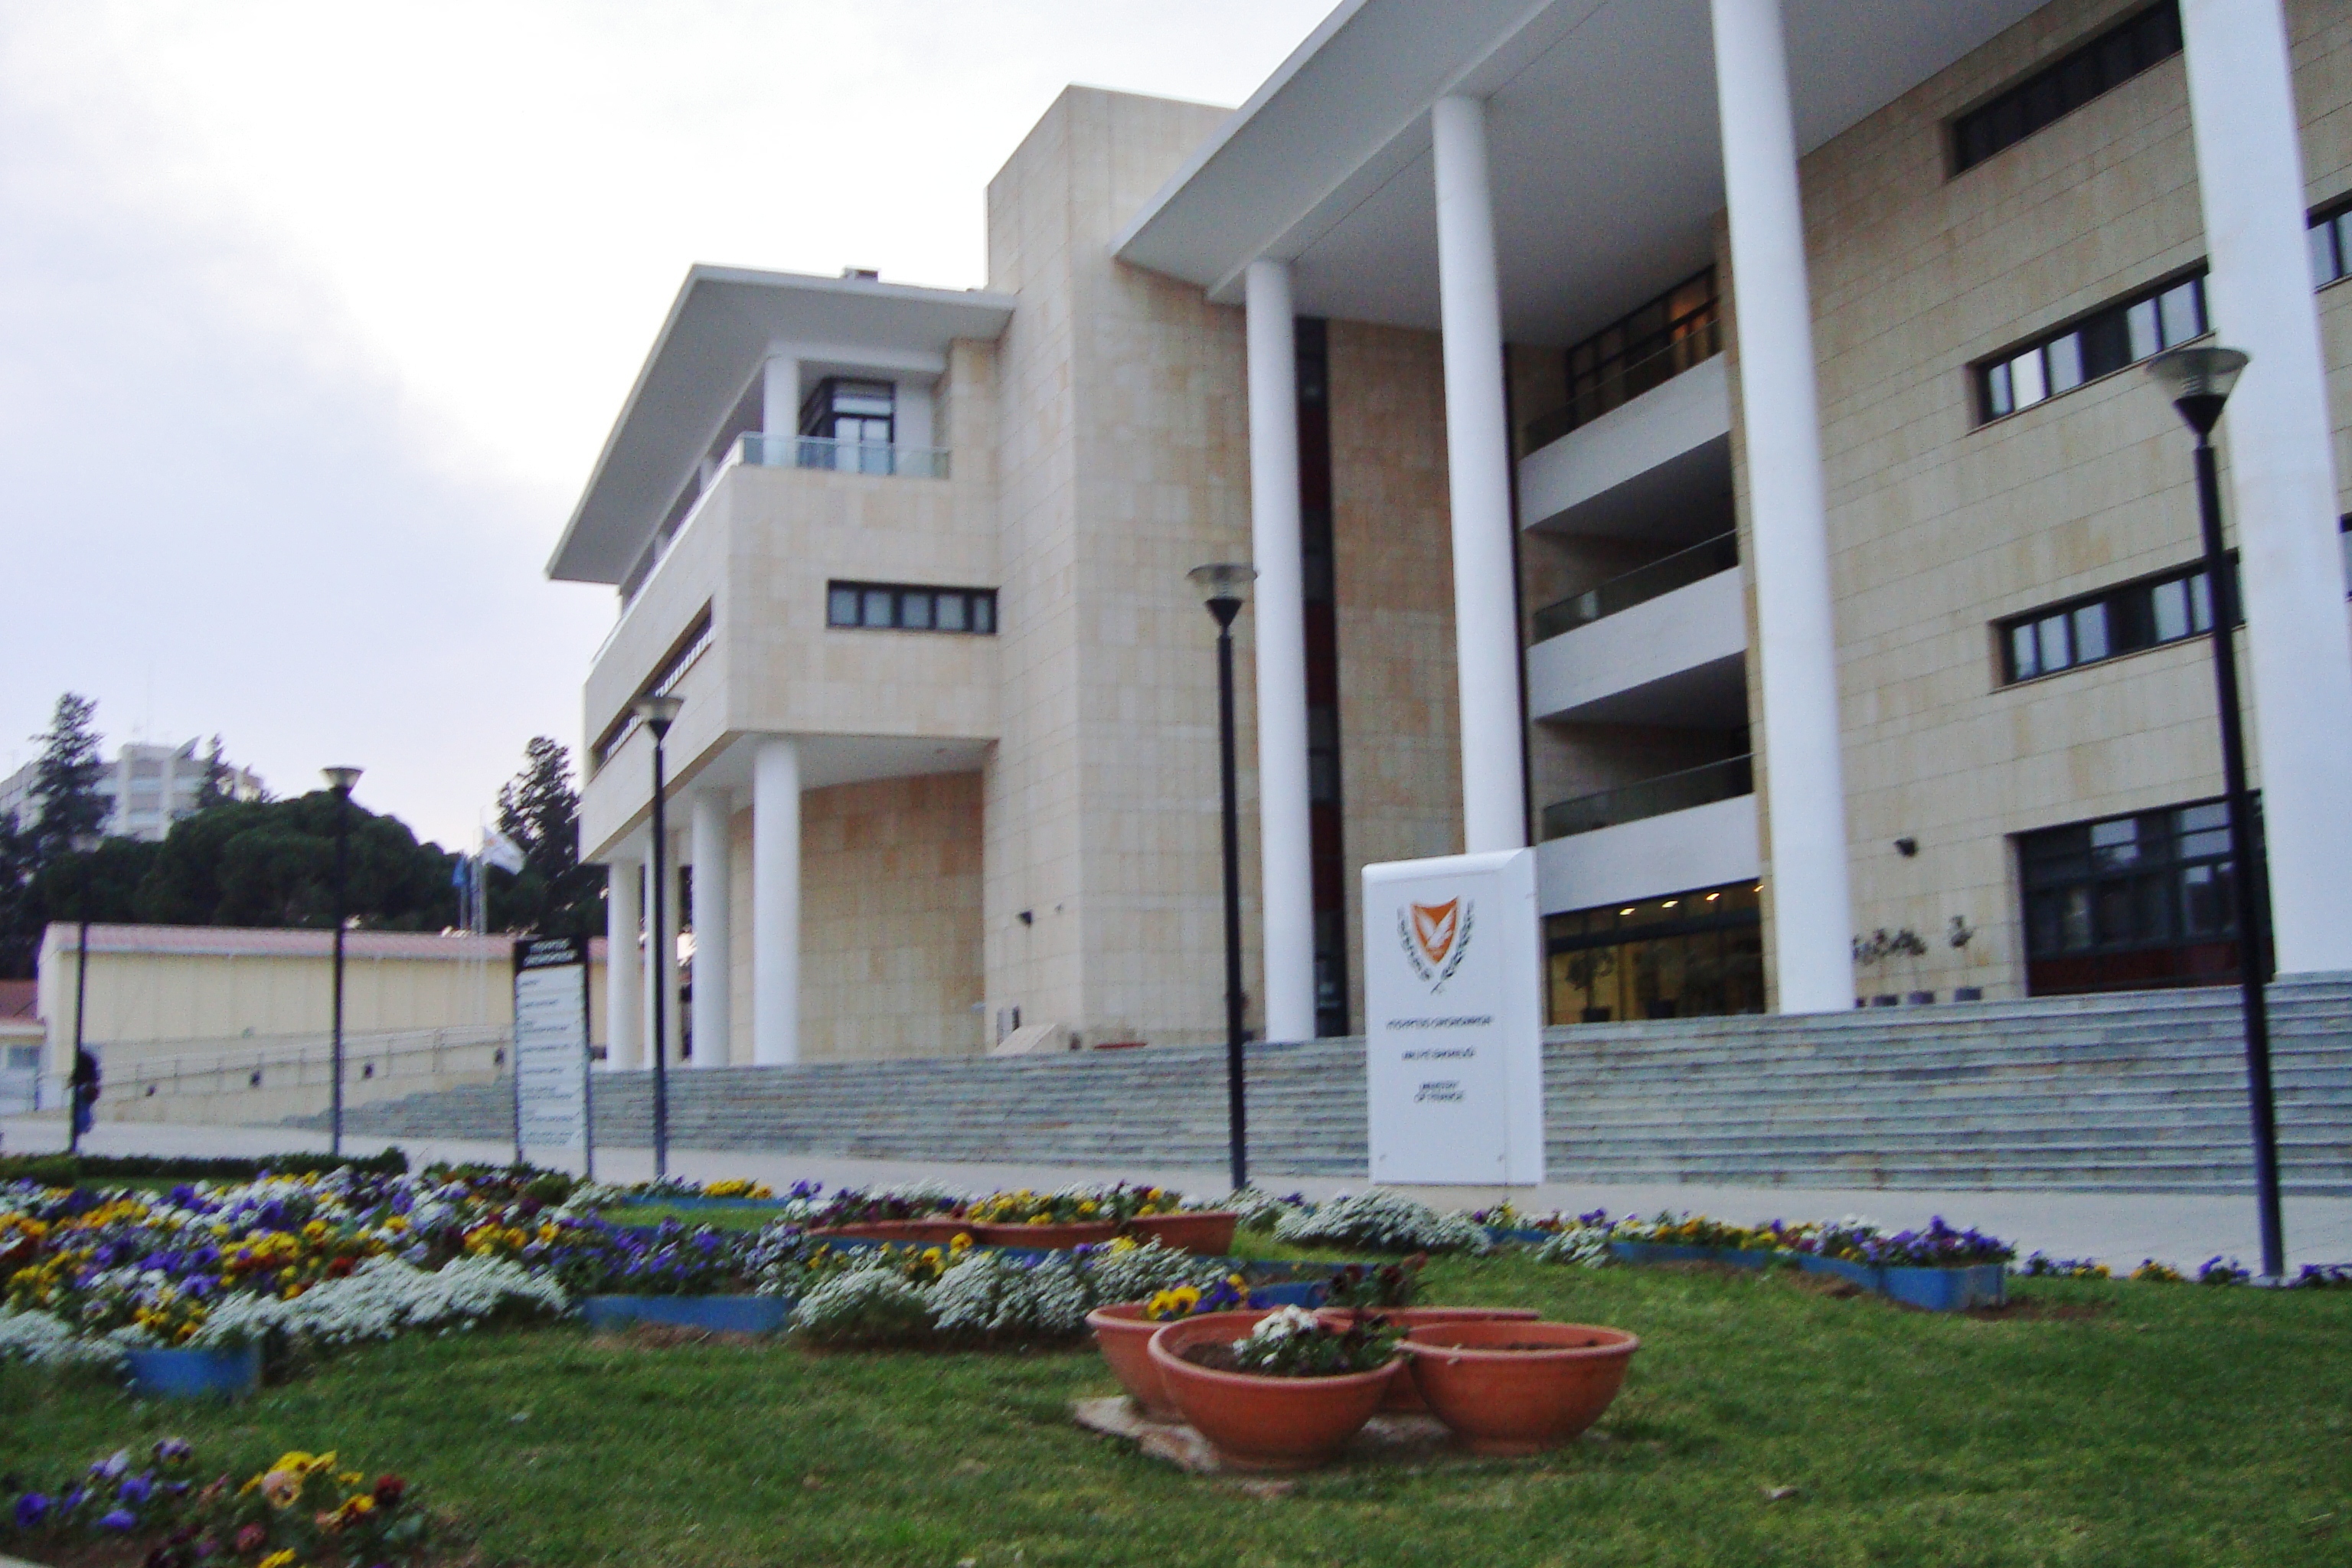
Should the EU bail-out Cyprus?

Cyprus Ministry of Finance. Source: Wikimedia Commons
From what I have seen, I was the first blogger to bring attention (on July 28th!) on the worsening situation in Cyprus and the imminent bailout. Media sources have had their reports before that of course but they were largely focused on Greece and the probabilities of a Grexit. Now, it is more than evident that Cyprus is having liquidity issues, largely due to their banks' exposure to Greece (both in sovereign debt as well as private loans). Now, as usual, many media sources have expressed their own views on whether the EU should lend the island money to overcome its difficulties. For example, the Wall Street Journal states that a line has to be drawn and Cyprus should be let to default.

It's always easy to hit the little guy isn't it?

For me, the rationale behind the statement "draw the line" is not very clear. Draw the line where? Let small economies collapse because their effect on the economy will not be as large as the effects of a Greek default? It is the same irrational rationale which has forced the US government to bail-out AIG, Bank of America, General Motors and about 15 other large institutions (for details on the TARP program read here). The message: do not worry if you are large; we shall do anything to save you. Yet if you are small, bankruptcy is your only option. Hmm that doesn't sound very democratic does it?

On the other hand shall we pay €18 billion to a country where the debt-to-GDP ratio is expected to rise over 130-140%? The answer is it depends. First of all the amount is ridiculous. 18 billion is approximately 100% of Cyprus's GDP! (for the calculation have a look at this) It is impossible for a nation to require that much money. Even if they did, the amount could easily come from the ECB's printing machine. Value of euros produced by the EU just in 2012: €184 billion. Cyprus requires less than 10% of that even at the utmost extreme scenario, which again is highly irrational.

Let us take things from the start. Cypriot banks stupidly put more than 50% of their equity in Greek government bonds. Then came the infamous Greek PSI. Had there not been for that, Cypriot banks would not have lost approximately €4 billion's worth of bonds, and they would not have been at the situation they are currently facing. Still one might add, that to the previously mentioned amount of €18 billion, the Troika delegates have calculated about €10 billion for bank recapitalization, and the rest for debt repayment and government needs. Let us examine them one by one.

First, letting the banks collapse should be out of the question. Bank default would cost much more than what it would take for them to recapitalize, even at the extreme scenario of €10 billion. Now let's examine this differently. The island current faces a debt-to-GDP ration of approximately 75% and has a deficit of about 4% of GDP. The latter figure is expected to be reduced to 2.5-3% in 2013 and even further by 2014. This would mean that essentially from 2015 onwards the Cypriot debt will start moving downwards. The issue is what happens until 2015.

What I would propose is in fact very simple. In addition it would only cost around €3 billion. From what I have been reading, Cypriot banks have issued about €1.2 billion in CoCo bonds (for a definition read this). So if they transform these bonds in ordinary shares, their equity base will be significantly strengthened, and they will surely need much less help in finding the necessary capital for them to continue functioning. In addition, another €3 billion should be lent to the Cypriot banks, conditional on the term that they should lend it back to the state to fund its needs. Given that the hole in the banks' balance sheets is about €2.5-3 billion, they would more than cover it with the €4.2 billion influx received, even given that the low ratings Cyprus has received from the ratings agencies. It is highly unlikely that the island would need more than €3 billion for the next year (or even the year after), provided of course that it can roll-over its current debt; which will have no trouble doing given that most of its lays in the hands of Cypriot banks and pension funds. 

In addition, given that Greece is on the verge of a crisis-reversal in 2013, banks would start receiving profits in either 2013 or 2014 from their exposure there, which they could use to directly fund the Cypriot state by 2015. Even if the huge influx of capital due to the gas depositories in the area does not occur, then by a combination of very few austerity measures and an increase in consumption (which will occur if banks influx just a percentage of that €4.2 billion back to the system) the future would be much brighter for the island than any other scenarios. What makes this plan even better is that the EU only has to lend the island about €3 billion, which is essentially nothing to them. Oh, and it can do so by directly funding the banks through the EFSF/ESM funds instead of just having €300 billion sitting around. 

The alternative presents a much darker situation: if Cyprus obtains a loan is excess of €10 billion, then another memorandum and a debt haircut are inevitable. This is not so difficult to see; we have the Greek experiment to indicate that these issues are not so incomprehensible and difficult to forecast as people who are just bored to think two moves ahead may believe. More so, it is their job to do so. (talking about the Cypriot and Irish minister here, who did not veto decisions which were aimed against their countries in two different Eurogroups. As Constantin Gurdigev has commented, their actions resemble the Stockholm Syndrome)

If they are denied of help then the Cypriots have two options: either default and stay in the Union, or exit the Union and avoid default. As forecasts state that there is enough natural gas in deposits near Cyprus to support probably half of Europe, politicians would not risk letting them leave the Union. Yet, Cypriot politicians might actually be too afraid for such a radical solution. These are the odds to which the game is played: the little guy, more often than not succumbs to the will of the big guy, so the latter obtains continuous small profits from their relationship. It is the same rationale with stock market: bets which bring small profits very often when the market seems to be listening to whims of investors. Occasionally though, the market decides it has had enough of them and takes a large fall. What do you think happens to the big guy then?

Thursday, 20 December 2012

The Cypriot Patient

Good news for the Greeks yesterday, as the S&P ratings agency has upgraded the nation by six notches, from "Selective Default" to a "B-", with a stable outlook. Hopefully, the agency can understand the situation better than everyone else, and the Greeks will be able to say that they have put the worst behind them as 2013 leaves. Yet, their neighbouring Cyprus now appears to have taken a harder hit than first expected: the approximate bail-out package just for bank recapitalization is expected to be about €10 billion, the second largest in history, measured as a percentage to GDP.

Newspaper cover from Cyprus. Source: cyprusgasnews.com
Data for the second quarter of 2012 have shown that so far the island has a 74.6% debt-to-GDP ratio, or approximately €13.2 billion (simple calculations can show that Cyprus's GDP is about €17.7 billion). If we just add the €10 billion to receive the amount would reach a staggering 130% debt-to-GDP ratio, or €23.2 billion. Although I cannot find the article now, I remember a Cypriot authority stating that the debt burden would not exceed 120% (or at least that's what he hoped for), a threshold over which debt is not considered viable any more. It would appear that this was just wishful thinking.

The interest rate for the €10 billion bailout is expected to be around 2.5%, as Finance Minister Vassos Shiarly expects. Although I would like to know where he got those expectations from, even if he is right, an island whose budget is around €9.5 billion, would have to pay about €250 million per year just on interest payments.

Is this sustainable then? The answer is it will depend on how the Cypriot economy will react to the fiscal adjustments (aka austerity measures) the government in association with the Troika has pushed through. The expected adjustment will reach 7.25% of GDP. Assuming that GDP only declines by 3.5% as expected, it would mean that the debt-to-GDP ratio will increase by more than 5%. Oh, and the careful reader will also note that in the above calculations the amount paid for debt refinancing and other government needs has not been added. Guess how the calculation for sustainability goes when another €6 billion is added on the tap. Yes, exactly like Greece's.

What many have not yet realized is that although bad spending policies by the government and bad decisions from the banks have worsened the problem in Cyprus, another culprit has to be the Eurogroup itself. Had the infamous decision for cutting Greek debt by 70% not been taken, the Cypriot banks would not have lost around €4 billion of hard-earned money. Instead, they are now eager to receive government support or they will have to be liquidated. (for more details on who to blame for the crisis read this).

Obviously, one would be insane not to assign blame to the politicians or the bankers, who have tolerated and promoted a policy of over-spending and over-lending for years. An asset bubble had been raging for years in the island, assisted by the bankers, land developers and foreign demand. Now that the time for things to go back to normal has finally come, people naturally hate it. Living in fantasy for too long will cause you to forget what reality really is. It appears that everyone seems to forget that a correction was bound to happen some time. For Cyprus, this time is now. Nevertheless, consequences would have been much easier had the Eurogroup not taken that decision. Not just for Cyprus but for the rest of Europe as well.

Nevertheless, Cyprus can feel that it has been treated unfair for two reasons:
1. The aforementioned Eurogroup decision has brought the crisis much faster than the economy expected it.
2. The Cypriot banks are not getting funded by the ESFM/ESM funds like Spain's but are forcing the government to assume responsibility for them.

Even if we accept that Cyprus had opted for a bail-out before Spain did, it would still appear that the EU has a strange way of operating the ESM: not depending on the bank or its significance in the local economy, but on a sovereign level. If a nation is more important than another, economic-wise, then it would appear that they will support it and let the other fall. Yet, this is not the solidarity the EU officials have been proclaiming and surely not the preservation of peace and equality, values for which it received the Nobel price earlier this month.

This sort of injustice sets a paradigm for the EU authorities: they operate exactly like national governments do: assist people in power, those who are economically strong or have good connections and do not pay much attention to "ordinary" people. They just do it on a wider scale. Is this the kind of governance that we should be happy about, or is this how the first visionaries saw the EU becoming? I would certainly hope not.

As for the sustainability of the Cypriot debt, it looks that history will be repeating itself: Greece and now Cyprus. A €16 billion package will not be enough if the banks are not directly funded by the ESM/EFSF. New memorandum will have to be signed soon, and debt reliefs will be implemented.

That is, unless they bring their minds about and decide to do what would really make the island's transition from recession to recovery easier. Otherwise, it would be recession to depression.

Friday, 5 October 2012

Terrible Calculations and Crisis History

In Thursday's article I gave some of the views Nobel laureate Joseph Stiglitz had on Europe. Notably, that austerity measures are causing the crisis and not the other way around. Who could disagree with that? A simple logical deduction will lead us to that. Let's see now the order things happened in the EU:

1. Sub-prime lending crisis in 2008, led by US banking and investment firms, and marked by the Lehman Brothers collapse in North America and the Northern Rock bankruptcy in the UK. (other financial institutions also failed in the EU, yet no-one was large in size). The sub-prime lending crisis had nothing to do with the now sovereign debt crisis. (it may have been the thing that pushed Greece over the cliff but this was not the cause that brought the Greeks at the brink of disaster. The Greek economy was unstable for years)

2. Greek scandal concerning the size of debt, deficit and GDP of the nation. (debt and deficit had been deflated while GDP inflated. Curiously, nobody was ever sentenced for this fraud) Greece opts for a bail-out from the EU and the IMF and the first austerity measures were put forward in the country.

3. Seeing that the debt-to-GDP ratio of Greece climbed even higher, regardless of the austerity measures (again, think about this: €100 debt with €100 GDP makes a 100% debt-to-GDP ratio. €100 debt with €80 GDP makes a 125% debt-to-GDP ratio. Unfortunately this was too much mathematics for the Troika and the expert economists to understand) the EU policymakers and Troika decided to give the Greek debt a haircut. The haircut consisted of 30% of the face value at first (i.e. for every euro the borrowers held they were going to get 70 cents) and then another 70% of the remaining later (i.e. instead of the 70 cents they were holding they were going to get just 21 cents).

4. This led to a significant shrinking of assets for the banks exposed to Greek debt (many of the Cypriot, Spanish and Italian banks as well as many German ones which curiously managed to sell most of their bonds), and with the new regulation raising capital reserves from 8% to 9%, banks were is serious need for money. 

5. Since many banks did not have sufficient capital reserves to allow them to function, they opted for a government bail-out. As banks are not really like any other firm (look here for more details) the nations had little option but to try and save them. However, the banks' needs being large, and the nations' debt being high made it more difficult for them to refinance. Thus, nations themselves needed to opt for a bail-out since their banks were dragging them along to the bottom.

Had the Greek haircut not occurred in such extremity (for an alternative read here), banking needs would have been lower and nations would not be in such a difficult state. Thus, the rough austerity measures could have been milder and with a longer time-span than now. This would have allowed nations to increase their GDP slowly, while simultaneously reducing their deficit and debt, which would mean that none of the current events would be happening. Although I am an advocate of the austerity measures in order to rationalize the budget, having too much too rapidly will only cause trouble in an already troubled economy.

P.S. The new idea now is that politicians and policymakers will offer more austerity with different measures than the ones the Troikans are proposing. Case study: Cyprus. The counter-measures proposed by the Cypriot government include a 9-11% cut in public servants wages (nothing of the kind was mentioned in Troika documents) in order for the Troikans to agree for the non-abolishment of the 13th salary (a bonus salary paid at the end of each year). Again simple maths: €1000 monthly salary is €12000 a year. A 9% cut would mean that €1080 euros are cut from the worker's salary each year. (provided that the 13th salary does not suffer the 9% cut as well). So in essence, the worker is giving up €1080 to receive €1000. (€1170 if the 13th salary suffers cuts as well). You may imagine what happens at the 11% level. 

Clear case of stupidity and obsession with an idea: the 13th salary should not be abolished, thus we are offering extra cuts, so that the 13th salary will remain but the overall hit would be larger than the one proposed by Troika. Hmm, one wonders who it is the officials work for. Troika would be much better in running Cyprus than its politicians.

Wednesday, 29 August 2012

Bank Bailouts: The Correct Way

Some time ago, a book I read stated that the very nature of capitalism was to allow firms to die without any consequences to the system. The author wondered why the same thing isn't possible with banking institutions. That author was Nassim Nicolas Taleb and the book was titled Black Swan. (However, I wouldn't really recommend the book) Although at first I thought the author was right, after considering it I realized that the banks are not at all like any other firm.

If tomorrow Google were to file for bankruptcy, the consequences would be a lack of a good search engine and thousands of Google employees left without a job (and you wouldn't be reading this!). Otherwise, no harm would be done to the ordinary person. Now imagine what would happen if one of the major banks were to collapse: millions of people would suddenly be worried of being left with little or no money (although a country guarantees approximately 100,000 euros of deposits by each person in each bank). In the end, people would get their savings back (expect the persons which had amassed millions who will only get 100,000), however, the whole procedure would be traumatic to the ones who were unlucky enough to get caught in it. Nevertheless, such a procedure is preferred to the cost of pumping a bank with new money every now and then just to sustain it.

Thus, the question becomes: When should banking institutions be rescued? The answer is simple, although it may be tricky to define at times: When they are solvent, largely problem-free and have faced trouble only as a result of an unpredictable event to which they bore minimal or no responsibility. This, for example, would be the case with most EU banks which suffered great losses from the Greek haircut (although there were other banks which had overextended credit over the years).

If a banking institution is thought to be worthy of rescue then the course of action should be by directly providing liquidity to them. This would mean that governments, Central Banks or (preferably) an institution like the ESM, should provide liquidity to the banks; with the latter issuing new shares with voting rights, committing to repurchase them at an amount obtained after accounting for a fixed interest rate, and agreeing that the institution's participation in the bank's equity capital would be reduced each year, thus making sure that the stream of payments from the bank to the state would be continuous. Even if government (or Central Bank) intervention in banking institutions is not considered a good thing, it is much better than merely purchasing preferred shares, as the very recent Barclay's example indicates. By agreeing to pay interest on the amount given to them and repurchasing those shares at fixed intervals, it is assured that the taxpayers' money is not just thrown down a bottomless pit, making the banks more careful in their future investments and gradually reducing government intervention within them.

Following this, the distressed bank should implement some austerity measures, either by cutting down salaries or other benefits or, better, by reducing its activities both at domestic as well as at an international level. Needless to say, the bank's heads at the time of government intervention should be replaced. The bank could spin-off some of its operations if they are profitable, however, this should be done in a way that the new company is an independent one and not with the bank still controlling a substantial interest in it. Likewise, the spin-off should not be sold to another bank as this would increase the other bank's risk of becoming too-big-to-fail.

In the case of the bank becoming insolvent, problem-ridden with issues which are not due to unexpected events (e.g. management issues, poor lending decisions, etc) then it should be let collapse just like any other ordinary firm. If the bank has some operations which are profitable and well-functioning, then these should be spun-off, or sold to another company, even though selling them to another bank should be avoided for reasons of the other bank becoming extremely large. What the reader may inquire is what if the second bank is already too big? What difference would it make if the profitable operation is sold to them? First of all, a new spin-off will require more employees (think of new management, trainees, secretaries, even cleaners) than if it is sold to another company where existing economies of scale would take over. This would have a positive effect on unemployment especially since other bank's employees are expected to be laid off as a result of the collapse. Then, even the acquiring bank is already too big, in what scenario would the government (or another institution) be spending less for stabilization: saving a 100 billion bank or a 105 billion bank? And remember that's billion...

Under the current scheme, most banks are either classified as too big to fail or too little to have any exposure. Take the UK for example where only 5 independent large banks exist, with the government having interest in two of them. What should have been done was to reduce the level of activities of the Royal Bank of Scotland and Lloyds Banking Group to levels where such intervention would be easier in the future, also allowing the creation of more banking institutions, which would promote a competitive environment instead of an oligopolistic one.